How to Access Property Records in Massachusetts

Massachusetts property records are public documents, meaning anyone can access them without a reason or special permission. They are readily available if you know where to look. When searching property records in Massachusetts, you have two primary sources: government offices and commercial resources.
Government Sources
Accessing records through the Massachusetts registry of deeds is easy because the information is public. You can access this data both online and in person.
 Online
You can obtain records in a few different ways. First, visit the Secretary of the Commonwealth of Massachusetts property search website. From there, you can search for your town to find the registry of deeds office where your property is recorded and visit them in person to request documents or search online.
When searching online through the Secretary of the Commonwealth of Massachusetts website, choose the registry of deeds office, then click Go. You will arrive at the Massachusetts Land Records website. You can search for reports by entering:
- First Name
- Last Name
- Business Name
- Document Type
- Town
- Recorded Date
You can print or download any documents that appear in your search results. Much of the information is available online; some documents are on microfilm, and some are only found in paper books.
 In Person
You can also visit any of the registry of deeds' offices in person to search for these reports. If you visit in person, you may have to wait for copies and pay a small fee.
- Barnstable Office
- Berkshire Middle Office
- Berkshire North Office
- Berkshire South Office
- Bristol Fall River Office
- Bristol North Office
- Bristol South Office
- Dukes Office
- Essex North Office
- Essex South Office
- Franklin Office
- Hampden Office
- Hampshire Office
- Middlesex North Office
- Middlesex South Office
- Nantucket Office
- Norfolk Office
- Plymouth Office
- Suffolk Office
- Worcester Office
- Worcester North Office
To find property survey records, contact the land court in the proper jurisdiction and file a request for copies of survey records and boundary disputes.
 Commercial Sources
Commercial services make it easy to find property and related documents quickly, saving you time. PropertyChecker.com offers nationwide property searches. Using PropertyChecker, you can search by address, parcel ID, owner's name, phone, or email, and you can save time by running unlimited statewide or local searches 24/7. Instead of visiting multiple websites or visiting various running around to local government offices, you can find all the data points you need in one comprehensive report.
Land Records in Massachusetts
In Massachusetts, real estate transactions and land history are maintained at the county level rather than by individual cities or towns.
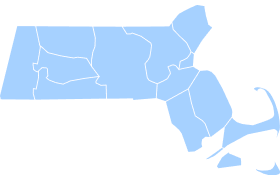
Massachusetts maintains land records through 21 separate registry districts, overseen by the Office of the Secretary of the Commonwealth. Each district is managed by a locally elected official known as the register of deeds. Although Massachusetts has only 14 counties, some geographically larger or highly populated counties are divided into multiple "districts." For example, Berkshire, Bristol, Essex, Middlesex, and Worcester counties each have multiple registry offices. To find a record, you must know exactly which specific district the property's town belongs to.
The most unique feature of Massachusetts property law is that it operates under two entirely different tracking systems. A single parcel of land can even contain pieces of both.
- Recorded Land (Approx. 80–90% of properties): This is the traditional, standard system used across the United States. The registry accepts real estate documents, verifies they meet formatting rules, stamps them chronologically, and files them using a book and page number. The state does not verify that the claims in the document are true; a title examiner must trace the chain of ownership and uncover hidden errors or liens.
- Registered Land (Approx. 10–20% of properties): Often referred to as the Torrens system, this setup is heavily overseen by the Massachusetts Land Court. If a boundary dispute or title issue arises, the Land Court formally steps in to legally resolve the issue once and for all. Once finalized, the state issues a Certificate of Title and a specific document number (instead of a book and page number). The Commonwealth of Massachusetts guarantees the title to registered land. If a hidden title issue pops up later, the state will financially compensate the owner. Documents filed on the registered side face much stricter compliance scrutiny before acceptance.
Massachusetts land records are widely available online. The state provides a centralized, free portal at MassLandRecords.com, which links out to all 21 registry databases. For standard, everyday property searches (using addresses or owner names), records are generally fully indexed and fully text-searchable back to around 1948 or the 1970s, depending on the county.
Many registries have digitized their historical books going back much further. For example, through MassLandRecords.com or historical partnerships like FamilySearch's Massachusetts Land Records Collection, you can browse scanned images of deed books stretching back to the 1600s and colonial times.
While modern records are uniform, online depth for old records varies wildly by county. For example, the Suffolk County database allows online searches going back the last 50 years. For historical or genealogical deep dives, it is still best to visit the registry in person.
Quick Reference: Beyond Standard Deeds
When exploring Massachusetts registries, you will encounter multiple legal filings that provide a deeper story about the property beyond the deed.
| Record Type | What It Tells You / What is Available |
|---|---|
| Mortgages & Discharges | Details historical loans, who lent the money, and precisely when the debt was completely paid off. |
| Plan Maps & Atlases | Hand-drawn or surveyed lot maps showing original property lines, neighborhoods, and older geographical markers. |
| Declarations of Homestead | Legal protections filed by homeowners to shield their primary residence from certain types of creditor lawsuits. |
| Zoning Decisions | Approved variances, special property permits, or land-use restrictions greenlit by local municipal boards. |
| Liens & Tax Attachments | Records of unpaid debts, contractor disputes, or unpaid municipal taxes tied strictly to the land. |
| Colony & Proprietor Records | For deep historical research, early land grants from the King or early colonial general courts (predating the official county system). |
In Massachusetts, subdivision plats are officially called plans, and they follow a specific system of recording, accessibility, and utility. Subdivision plats are filed at the registry of deeds for the county or specific district where the land is located.
Before a subdivision plan can be recorded at the registry, it must first be approved by the local municipal Planning Board under the Massachusetts Subdivision Control Law (M.G.L. Chapter 41). The final plat will include a signature stamp from the Planning Board, allowing it to be recorded.
The vast majority of Massachusetts land records, including recorded plans, can be accessed through the official centralized portal, Massachusetts Land Records. Once you select the correct registry district on the portal, change your "Search Type" dropdown from "Recorded Land" (which looks up names and deeds) to "Plans." You can then search for plats.
While modern plans are 100% digitized, if you are looking for an older layout (pre-1950s), some districts may require you to email their plan department to retrieve the scan.
Rural parcels often rely on dirt tracks or paper roads. A plat map will explicitly outline whether a road is a public right-of-way, a private way, or a dedicated easement.
Rural Massachusetts is full of centuries-old cart paths and agricultural easements. A recorded plan is one of the best ways to see if a utility company, a neighbor, or a logging outfit has legal rights to cross your vacant land.
You can use the parcel dimensions from a plat map to cross-reference the Massachusetts Interactive Property Map (MassGIS). This allows you to overlay state environmental layers onto the parcel to check for wetlands, protected zones, or endangered habitats.
For land records predating 1900 in Massachusetts, the primary sources are the county registries of deeds (and their specialized district offices). Unlike many states that kept land records strictly at the town level, Massachusetts established a county-based public land recording system under the First Modern Recording Act of 1640.
What Are Property Records?

Property records in Massachusetts are legal documents that contain information about a piece of real estate within the state. They include both vacant plots of land and those with buildings or homes. Such reports are vital because they prove that you legally own your home.
Don't confuse property records with land records. The two are different. Land records detail land ownership. Along with who owned the land, you might also see spouses' names, heirs, other relatives, and even neighbors' information.
When a property changes hands, a new deed is filed with the county register of deeds. Once recorded, it becomes legally binding.
What Information Can You Find in Massachusetts Property Records?
Along with finding the homeowner, some of the information you can find on Massachusetts property records includes:
-
 Liens
-
 Tax Records
-
 Ownership History
-
 Mortgage / Loan Records
-
 Foreclosures
-
 Plat Maps
-
 Easements / Conveyances
-
 Property Details
-
 Zoning
-
 Building Permits
-
 Boundary Lines
-
 Assessed Values
-
 Deeds
-
 And More!
Who Looks Up Massachusetts Property Records and Why
Every day, people look up Massachusetts property records to review tax records, check for mechanic's liens, code violations, easements, deed restrictions, boundary lines, hazardous waste, and property values. Some real-life scenarios of individuals checking property records are below:
-
 Home Buyer - A home buyer is looking at a triple-decker home in Worcester; a classic Massachusetts property type she hopes to live in while renting out the other units. She pulls the local registry of deeds records to check for any outstanding mechanic's liens or historical code violations. This matters to her because Massachusetts has strict landlord-tenant laws, and she wants to ensure she isn't inheriting costly legal or structural headaches before making her first down payment.
-
 Investor - An investor wants to purchase a multi-family property in Quincy to capitalize on the high rental demand near the MBTA Red Line. He searches the land court records to verify the property's clean title and check for any easements or historical deed restrictions. Hidden restrictions could block his plans to add off-street parking, a premium commodity in the Boston metro area that heavily drives up rental value.
-
 Homeowner - A homeowner wants to build a detached backyard cottage on her property to house her aging parents, taking advantage of a local zoning change. She reviews her property's original plot plan and deed history at the Hampshire County Registry of Deeds to pinpoint her exact boundary lines and confirm there are no conservation restrictions. An unrecorded boundary dispute or a setback violation could halt construction entirely or force her to tear down an expensive structure.
-
 Real Estate Developer - A real estate developer is eyeing an old, abandoned textile mill along the coast to convert into modern waterfront lofts. He reviews decades of property tax and ownership records to see if the site was ever flagged under Chapter 21E, the Massachusetts law regulating hazardous waste and oil releases. This is crucial because discovering past industrial contamination lets him estimate cleanup costs and negotiate a lower purchase price before committing millions of dollars to the redevelopment.
-
 Tax Assessor - A tax assessor needs to update property valuations across Cape Cod following a year of intense market demand for coastal homes. She reviews recent property deeds, sales prices, and building permits to determine how much a home's value increased after a major renovation. State law requires regular, fair-market assessments to ensure the town's property tax burden is distributed accurately and legally among all residents.
Types of Property Records in Massachusetts
Within property records, you will find varying degrees of information. Some of the more common types you can expect to see are:
Deeds and Conveyance Records
Deeds are legal documents proving ownership. Conveyance documents are a blanket term covering the many ways owners can transfer title, ownership, or property. Both the seller (grantor) and buyer (grantee) must sign the sales deed.
Deeds in Massachusetts include the following information:
- Property Identification - The document identifies the property to be transferred via parcel number, address, and legal description.
- Names of Parties Involved - The deed names the parties involved, their roles, and the grantor/seller and the grantee/buyer.
- Title - The document states the type of title being conveyed, e.g., easement or estate.
- Covenants - The deed may include promises the grantor makes about the property.
- Considerations - The document specifies the purchase price of consideration.
- Signature and Notarization - Like other legal documents, deeds in Massachusetts have signatures and, in some cases, notarization.
Property Liens and Encumbrances in Massachusetts
An encumbrance is a claim against a piece of real estate by someone who is not the owner. They can affect home transfers and sales. The most common types are mortgages, liens, and easements.
Voluntary Liens
Voluntary liens like mortgages are those that you choose when using your property as collateral against a loan.
People who borrow money to purchase property hold a mortgage from the lender. The lienholder (lender) puts a lien on the property until the mortgage is paid off. If the owner defaults on their mortgage, the lender can force foreclosure.
Involuntary Liens
Involuntary liens are those over which you have no control. They are imposed because of a debt you owe. There are three types:
- Mechanic's Liens - When a contractor does work on a piece of property and the owner fails to pay them, they can put a mechanic's lien on the property.
- Tax Liens - Tax liens are imposed by government offices (local, state, federal) for unpaid taxes.
- Judgment Liens - Judgment liens arise from a court order when a creditor sues the homeowner in court for a debt they failed to pay
Liens are legal claims against a specific piece of real estate. A lien gives a creditor the right to seize the property should the debtor fail to pay a debt.
Easements and Covenants
An easement is a legal right to use a parcel for a specific purpose. A "right of way" allows someone to cross into someone else's land. A restrictive covenant legally stipulates how the land may be used. Covenants exist most often in gated communities and condos.
Plats and Surveys
A plat is a map that shows the boundaries of a tract of land. A survey, however, is a more detailed map showing a single plot of land. Title companies most often use surveys before issuing title insurance.
Property survey documents include information related to the property boundaries, features, and topography, such as:
- Easements and Rights of Way - The survey may show the location of any rights-of-way or easements.
- Property Lines - The document often shows the location of property lines, including corner markers.
- Boundary Disputes - The survey will note any ongoing disputes or discrepancies.
- Topography - Some surveys have a topographic map showing the contours and elevations.
Information on property surveys differs depending on the surveyor or surveying company.
Property Descriptions and Boundaries in Massachusetts
A property deed will include the legal description of the plot of land and any buildings on it. If the property is registered, the land court will have surveys and land measurements for the property in question. Since boundary disputes and resolutions are court-related, you can find those with the land court office. You must complete a form for a copy of the land survey and boundary dispute records. Some of these documents cost a small fee.
Foreclosures
Foreclosure is when a bank or lender repossesses a home when the owner fails to pay the mortgage. Each registry of deeds office has lists of foreclosures; you can access them through the Secretary of the Commonwealth of Massachusetts website.
Massachusetts Pre-Foreclosures for Investors
In Massachusetts, the foreclosure process is "non-judicial," meaning lenders usually do not need a judge's permission to hold an auction and sell a home. The process is more streamlined and efficient.
The Signal That Starts the Clock
The official foreclosure clock starts when the lender sends a formal "Right to Cure" notice. Under Massachusetts law, if a homeowner defaults on their mortgage, the lender must send this notice and give the homeowner 90 days to pay the missed amount and bring the loan current. This window is the "pre-foreclosure" phase.
The pre-foreclosure window is an ideal opportunity for investors to research the property and contact the owner with a fair offer. It helps the owner avoid foreclosure and can provide a profitable win for the investor.
The Foreclosure Timeline
A typical residential foreclosure in Massachusetts takes 6 to 9 months from the first missed payment to the actual auction. The timeline generally goes as follows:
- Day 1–120 (Delinquency): The homeowner misses payments. Federal laws usually prevent lenders from starting the official legal foreclosure process until the loan is more than 120 days late.
- The Right to Cure (90 Days): The lender sends the Right to Cure letter. If the homeowner cannot pay the past-due amount by the deadline, the lender will "accelerate" the loan, meaning they demand the entire remaining mortgage balance, not just the missed payments.
- The Servicemembers Case (1–4 Months): Before holding an auction, the lender files a quick case in the Massachusetts Land Court. This is done strictly to prove the homeowner is not active-duty military, as service members have special legal protections against foreclosure.
- The Public Notice (3 Weeks): Once approved, the lender schedules the auction. They must publish a notice of the sale in a local newspaper once a week for 3 consecutive weeks and mail a notice to the homeowner at least 14 days before the auction.
- Homeowner Notice (14 Days Before the Auction): The lender must send the homeowner the auction notice via registered mail at least 14 days before the sale.
How the Auction Works
The foreclosure auction is a public event that almost always takes place right outside the property, typically on the sidewalk or driveway. An official, licensed auctioneer conducts the sale. Bidders gather outside; they are not allowed to go inside the house to inspect it.
The property is sold completely "as-is," often with the previous occupants still living inside.
The lender may bid, and if no one bids higher than the mortgage amount, the lender buys the property back and takes ownership. At that point, it becomes Real Estate Owned (REO), and the lender can sell it privately or via another auction.
To bid at a Massachusetts foreclosure auction, buyers must bring a significant upfront cash deposit. The exact amount is specified in the newspaper ad but is typically $5,000 to $10,000 (or more for luxury properties).
If you are the winning bidder, you must hand over this deposit immediately on the spot right after the auctioneer's gavel falls. It must be paid in a certified format, usually a bank treasurer's check or a certified check made out to the foreclosing law firm. They do not accept cash or personal checks. The winning bidder must sign a "Memorandum of Sale" right there on the street. They then typically have 30 days to pay the remaining balance of their bid. The remaining balance is paid at a formal closing via a bank wire transfer or another certified bank check.
The winning bidder is responsible for buying the property subject to any outstanding municipal liens, back taxes, or water/sewer bills. If the buyer fails to pay the remaining balance within 30 days, they forfeit their entire upfront deposit, and the property may be offered to the second-highest bidder.
In-Person or Online
Massachusetts foreclosure auctions take place in person. Unlike states that hold centralized auctions on courthouse steps or entirely online, Massachusetts mortgage foreclosure auctions are typically held directly on-site at the property being foreclosed.
Although the initial foreclosure auction must be attended in person, you will often see Massachusetts foreclosures listed on online platforms like Auction.com or ServiceLink Auction. These online events are bank-owned (REO) auctions. If no third-party bidder buys the property at the initial in-person foreclosure auction, the bank buys it back. Once the bank takes full ownership, it often lists the property on online auction portals to sell it to the public.
Buying and Selling Property in Massachusetts

Buying and selling property comes with specific responsibilities. Due diligence refers to the time period between when you place an offer on the home and when you close.
The lender may require you to purchase title insurance if you obtain a mortgage on the property. The title company will perform a title search to see if the title is clean.
When selling property in Massachusetts, you must provide disclosure documents to the buyer. In Massachusetts, that includes:
- A lead paint disclosure stating whether lead paint has ever been used on the land.
- Verification that a septic system is installed.
Before buying any property in Massachusetts, check property records for any liens, outstanding loans, easements, covenants, and title issues to prevent problems.
How Property Transfer Works in Massachusetts
In Massachusetts, transferring real estate and personal property requires following strict state rules. If you plan, the process can be simple. However, skipping these steps can lead to a lengthy and expensive court process for your family.
Transfer-on-Death (TOD) Deed
Massachusetts does not allow transfer-on-death (TOD) deeds for real estate. While about 30 states let you sign a piece of paper that automatically hands your house to a beneficiary when you die, Massachusetts is not one of them. However, Massachusetts does allow TOD and Payable-on-Death (POD) designations for financial accounts (like stocks, bonds, and bank accounts). For a house, you must use alternative options to keep it out of court, such as adding a co-owner with "rights of survivorship" (like tenancy by the entirety for married couples) or placing the house inside a revocable living trust.
Transfer Tax
Transferring property in Massachusetts triggers a few specific costs. The state does not have a gift tax or an inheritance tax, but it does have other transfer costs such as tax stamps, estate tax, and probate costs. When real estate is sold or transferred for consideration, the state charges a transfer tax. In most Massachusetts counties, this costs $4.56 per $1,000 of the property's value (Barnstable County charges higher rates). You generally do not owe this tax if you are passing property to an heir through a will or trust without money changing hands.
If the total value of everything the person owned (including their house, cash, and life insurance) is over $2 million, the estate must file a Massachusetts Estate Tax Return.
If an estate ends up in probate court, expect to pay court filing fees (ranging from $100 to several hundred dollars), publication fees, and potentially thousands of dollars in attorney fees to handle the paperwork. Furthermore, the state places an automatic tax lien on all real estate when someone dies, which requires a specific filing to clear before the house can be cleanly sold.
What Happens When Someone Dies Without a Clean Transfer?
When a person dies, and their property does not have a built-in mechanism to transfer automatically (like a trust or a joint owner), the property becomes "trapped" in their individual name. To untangle this and legally change the name on the deed or bank account, the family must go through probate court.
If There Is a Will
The court reviews the will to verify it is authentic and officially appoints a personal representative (formerly called an executor) to carry out the will's instructions.
If There Is No Will (Intestate)
If someone dies without a will, it is called dying intestate. The state does not take the house, but Massachusetts intestacy laws dictate exactly who gets the property based on a strict family hierarchy (spouse, children, parents, etc.).
Even if everyone agrees on who should get the property, nobody has the legal authority to sign a deed or sell the house until the probate court formally appoints an administrator. This process typically takes months to over a year, during which time the house cannot be sold, and bills must still be paid.
Simplified Process for Small Estates
Massachusetts offers a simplified court procedure called voluntary administration for small, straightforward estates. The entire personal property estate must be valued at $25,000 or less (excluding one automobile). The estate cannot include any real estate property. Heirs can file after 30 days have passed since the person died before using it. An eligible petitioner fills out a Voluntary Administration Statement (Form MPC 170) and files it with the Massachusetts Probate and Family Court along with the death certificate.
Why Property Values Are Important in Real Estate Transactions
Individual jurisdictions (usually towns/cities) routinely assess local property to set tax rates. An appraisal is relevant to the real estate market. During a real estate transaction, the lender orders an appraisal to ensure the home's fair market value supports the loan.
The information contained in property records helps both assessors and appraisers to make an accurate valuation.
What Factors Determine Property Values in Massachusetts
High prices in some cities of Massachusetts are often determined by factors such as:
-
 Location - Cities closer to the major economic and cultural hub, Boston, offer convenient access to job opportunities, entertainment, and other amenities.
-
 Schools - Public school systems in these areas are highly regarded, attracting more attention from families.
-
Housing - Older homes in some cities like Lexington are considered unique because of their historical or architectural significance, which can contribute to higher value.
-
 Crime Rates - Places with higher crime rates are often considered less desirable than areas with lower crime. Therefore, property values in those areas tend to be higher since many homebuyers are willing to pay more for lower crime rates.
-
 Zoning laws and regulations - For example, properties zoned for commercial use may be worth more than similar properties zoned for residential use because of their investment potential.
-
 Population - The area's population may also affect property values within the city or town. For example, Marblehead is a coastal town in Massachusetts with a population primarily consisting of young families. Therefore, family homes in the area may be more valuable because they are in higher demand.
Massachusetts Flood Zones
Massachusetts faces an ongoing and growing flood risk from heavy storms, rising sea levels, and overflowing rivers, especially along the coast and major waterways.
High-Risk Regions in Massachusetts
- Coastal areas: Boston, the North and South Shores, Cape Cod, and the islands face severe risks from ocean storms and high tides.
- River valleys: Towns near the Merrimack River and Connecticut River face high risks when heavy rain causes rivers to overflow.
FEMA labels high-risk areas as Special Flood Hazard Areas (SFHAs). This means the area has a 1% chance of flooding in any given year. This is often called a 100-year flood. If your home is in an SFHA and you have a federally backed mortgage, federal law requires you to buy flood insurance.
Common Flood Zones Explained
- Zone AE: This is a high-risk flood area where water levels and base flood heights are calculated. Flooding here is usually standing or slow-moving water. Flood insurance is required with a mortgage.
- Zone VE: This is a high-risk coastal area. It faces extreme danger from fast-moving storm waves in addition to rising water. Flood insurance is required with a mortgage.
- Zone X: This is a moderate-to-low-risk area. It sits outside the main flood hazard zones. Federal law does not require flood insurance, though storms can still cause unexpected water damage.
What a Buyer Should Do Before Closing
- Check the property address on the FEMA Flood Map Service Center to see the exact zone. Also check Flood Insurance Rate Maps (FIRM) to review elevation levels and potential rates. However, remember that these maps change over time, and a property in a low-risk zone could suddenly be in a high-risk zone.
- Ask the seller for past flood history and proof of previous claims.
- Ask the seller for an Elevation Certificate to measure how high the lowest floor sits above expected flood levels. An elevation certificate is an official document from the Federal Emergency Management Agency (FEMA) that records a building's height compared to the estimated height of floodwaters in a specific area. A buyer needs one to determine their true flood risk, calculate accurate flood insurance costs, and satisfy mortgage lender requirements if the property sits in a high-risk flood zone.
- Call an insurance agent to get a flood insurance quote so you know the real yearly cost before you buy. Your options are the National Flood Insurance Program (NFIP) or private insurance. With NFIP insurance, you may pay less, but you must wait for coverage, and the program caps coverage limits. You may have better luck with private insurance if you need it quicker or higher limits.
Local Rules, Timelines & Fees
In Massachusetts, real estate transactions follow a unique mix of traditional legal principles and strict procedural timelines. Unlike many states where escrow companies handle closings, Massachusetts requires an attorney to oversee real estate transactions and handle the closing.
Massachusetts Unique Real Estate Rules
- What is unique about Massachusetts real estate transactions? In Massachusetts, buying a home involves signing two distinct contracts, not just one. First, the buyer must sign an Offer to Purchase (OTP). It locks in the purchase price, sets the timeline, and requires a small initial deposit (usually around $1,000). While it sounds preliminary, the OTP is a legally binding contract in Massachusetts. Then the Purchase and Sale Agreement (P&S) is signed roughly 10 to 14 days after the offer; the P&S replaces the OTP. It is a highly detailed, comprehensive contract drafted and negotiated by the buyers' and sellers' attorneys. At this stage, the buyer puts down the remainder of their down payment deposit (typically 5% of the purchase price).
- Does Massachusetts require an attorney at closing? Massachusetts is an attorney-state. By law, a licensed Massachusetts attorney must conduct the closing, witness the signing of the deed and mortgage notes, clear the title, and ensure the funds are properly disbursed.
- What does Caveat Emptor mean? Massachusetts strictly enforces a legal doctrine known as caveat emptor, which translates to "let the buyer beware." Sellers are not legally required to volunteer or disclose defects about the home's condition, even if they know about them. They only must answer questions honestly if asked directly. If they lie, it is fraud; if they stay silent, it is generally legal.
Foreclosure Type and Timeline
- Is Massachusetts judicial or non-judicial? Massachusetts is primarily a non-judicial foreclosure state that relies on a contract clause known as the Statutory Power of Sale. Lenders do not need full court supervision to auction a home, making the timeline relatively fast once it begins.
- What is the typical timeline from filing to auction? The typical timeline from officially filing or initiating the legal foreclosure process in Massachusetts to the actual auction date is about 4 to 6 months, assuming the pre-foreclosure notice periods have already concluded. If you count from the very first missed payment and the mandatory pre-foreclosure notices, the entire process spans 6 to 12 months.
Redemption Period
- Does Massachusetts allow the owner to reclaim the property after the sale? There is no right of redemption after a valid non-judicial foreclosure auction. Once the hammer falls, the owner loses control of the home, and the buyer can take ownership.
- How long and under what conditions? In a municipal tax foreclosure, if a city or town records an "Instrument of Taking" for unpaid property taxes, the town holds a "tax title". The property owner has a minimum 6-month redemption window to pay back all taxes, interest, and legal fees to the municipal treasurer. Only after 6 months can the municipality petition the land court to permanently foreclose the right of redemption.
Lien Deadlines and Priorities
- How long does a contractor have to file a mechanic's lien in Massachusetts? Contractors must record a "Notice of Contract" 60 days after a Notice of Substantial Completion is recorded, 90 days after a Notice of Termination is recorded, or 90 days after the last day labor or materials were furnished to the project.
- What is the process of filing a mechanic's lien in Massachusetts? Contractors and suppliers use mechanic's liens (formally called a Statement of Account) to secure unpaid balances for property improvements. Massachusetts enforces a two-step recording process with strict deadlines. After recording the Notice of Contract, the contractor must record a "Statement of Account" detailing the exact amount owed no later than the earliest of 90 days after a Notice of Substantial Completion, 120 days after a Notice of Termination, or 120 days after the last day labor or materials were provided. To prevent the lien from automatically expiring, the claimant must file a lawsuit within 90 days of recording the Statement of Account and record a certified copy of the complaint at the registry within 30 days of filing the suit.
- What are the HOA attachment rules and timelines in Massachusetts? In Massachusetts, the laws and timelines governing property attachments and liens differ drastically depending on whether the property is a condominium or a traditional single-family home within a Homeowners Association (HOA). While condominium trusts have strong statutory protections under the Massachusetts Condominium Act (M.G.L. c. 183A), traditional HOAs do not automatically receive them and must follow standard civil court procedures. Under Massachusetts law, condo associations possess a super-priority lien. This means their lien takes priority over even the first mortgage on the unit for up to six months of regular, budgeted condo fees, plus collection costs and attorney fees. Interest, late fees, and special assessments do not get super-priority status. After 60 days of delinquency, the association can officially begin the process. They must perform a title search and send a 60-day statutory notice via certified and first-class mail to the first mortgage holder (lender). Thirty days later, the association must send a 30-day statutory notice directly to the unit owner outlining the debt and intent to file suit. If the debt is not paid, the association files a judicial enforcement action in court to perfect the lien and initiate foreclosure. Once the lawsuit is filed, an attested copy of the complaint (including a description of the property and amount due) must be recorded at the registry of deeds within 30 days - this is the most crucial deadline. If the association misses this window, the lien is completely dissolved.
Deed and Transfer Costs (Recording Fees and Transfer Tax)
- What does it cost to record a deed? Recording a deed in Massachusetts costs a flat fee of $155. Recording a mortgage costs $205.
- Is there a documentary stamp tax or transfer tax? When transacting property, the costs are split between state tax stamps (primarily a seller expense) and standard recording fees (primarily a buyer expense).
- What is the rate? The standard statewide rate for deeds excise tax (tax stamps) is $2.28 per $500 (or $4.56 per $1,000) of the property's purchase price, rounded up to the nearest $500 increment. Transactions under $100 are exempt. However, Barnstable County (Cape Cod) charges a higher rate of $3.24 per $500 to fund local water protection. Dukes County (Martha's Vineyard) and Nantucket County impose an additional 2% Land Bank fee paid by the buyer.
Maintaining and Amending Massachusetts Records
With so many real estate transactions, sometimes property records need to be corrected. An error could be as simple as a misspelled name, incorrect address, or property description.
You can't change an existing deed with errors, but you can amend it with a corrective deed. A corrective deed does not affect the home's title.
To update your records when someone dies, your attorney can draft a new deed removing the deceased person.
The Role of the Registry of Deeds

The registry of deeds in Massachusetts is the official office that records deeds for property within state limits. Each recorder of deeds records each property transaction. Each county has its own registry of deeds office, and the Secretary of State oversees all offices.
Massachusetts has two types of deed recording systems for real property: recorded land and registered land. Most Massachusetts land falls in the recorded land system (80–90%).
How to Ensure Data Privacy for Property Records
Most property records are public and may expose personal information about the owner. Some ways to keep your information private are:
- When buying real estate, do so under an LLC, revocable trust, or realty trust, also known as "land trusts" or "nominee trusts".
- Ask your mortgage company to keep your personal information confidential.
- When paying tax bills, pay with something other than a personal check.
- Purchase property under a business name or trust to protect your personal information.
- Constantly monitor your credit reports and limit how much personal information you share.
- Request that extra details be removed from public records.
As a member of the public, you have a legal right to access all public property records and their information.
- 500 Cummings Center Suite 6500,
Beverly, MA, 01915 - (617) 356-0899
Instant Access to Massachusetts Property Records
- Owner(s)
- Deed Records
- Loans & Liens
- Values
- Taxes
- Building Permits
- Purchase History
- Property Details
- And More!
Property Records Guide
- How to Access Property Records in Massachusetts
- Land Records in Massachusetts
- What Are Property Records?
- Who Looks Up Massachusetts Property Records and Why
- Types of Property Records in Massachusetts
- Buying and Selling Property in Massachusetts
- How Property Transfer Works in Massachusetts
- Why Property Values Are Important in Real Estate Transactions
- Massachusetts Flood Zones
- Local Rules, Timelines & Fees
- Maintaining and Amending Massachusetts Records
- The Role of the Registry of Deeds
- How to Ensure Data Privacy for Property Records
Property Records Guide
- How to Access Property Records in Massachusetts
- Land Records in Massachusetts
- What Are Property Records?
- Who Looks Up Massachusetts Property Records and Why
- Types of Property Records in Massachusetts
- Buying and Selling Property in Massachusetts
- How Property Transfer Works in Massachusetts
- Why Property Values Are Important in Real Estate Transactions
- Massachusetts Flood Zones
- Local Rules, Timelines & Fees
- Maintaining and Amending Massachusetts Records
- The Role of the Registry of Deeds
- How to Ensure Data Privacy for Property Records